
We are used to hearing that digital asset integration is a slow, lengthy process, but forex brokers have demonstrated that it doesn’t have to be the case. Many already accept stablecoin deposits, and a growing number are rethinking how money moves through the entire business.
London's trading industry is coming home!
That’s because forex has a completely different business model from, say, banks. FX is a channel-driven business. Brokers don’t rely on technological advantages in the same way banks and fintech firms do, so they have long assembled their technology from vendors. They’re used to third-party intermediaries handling deposits and withdrawals on their behalf.
But as digital asset volumes have grown, more mid-sized and large brokers have started rethinking their strategy. No longer satisfied with simply plugging into payment gateways controlled by third parties, leading forex brokers are partnering with crypto infrastructure providers to build their own blockchain tools.
A Business Built on Someone Else’s Stack
Traditionally, banks have treated their core technology stack as a strategic asset. Ledgers, payment systems and account infrastructure are built in-house, and changing anything is a major undertaking. Digital assets don’t slot neatly into that architecture, so adoption becomes a transformation project.
Forex brokers grew up differently. Trading runs on MetaTrader. Customer management sits in a third-party CRM. Execution comes from external liquidity providers. Deposits and withdrawals flow through outside payment gateways. A typical brokerage is a set of specialised providers stitched together with APIs, and its operators are fluent in integration.
- Brokers Spent 2026 Plugging Into AI Assistants. A London Summit Panel Asks What Comes Next
- Vietnam Hands “Mr Pips” Life Term in $60 Million Forex Fraud Case
- Weekly Review: eToro Crypto Trades Fall 62%; IG Group Secures Court Approval for Jersey Move
The appeal of this strategy is obvious: it is fast to deploy and cheap to build. For small and mid-sized brokers, all it takes is a quick integration to go live, which is why this became the default approach across the industry for years.
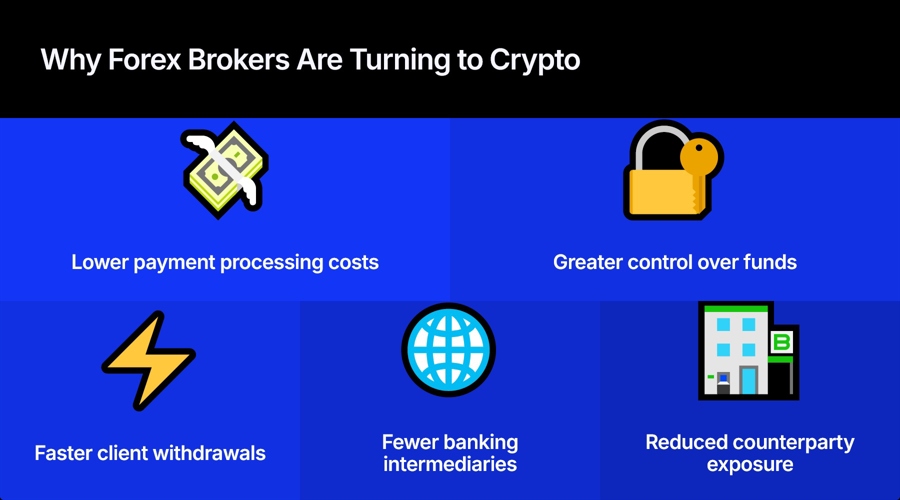
However, the cost model breaks down at scale, comes with custody and counterparty risks, and ultimately affects the user experience. Digital asset infrastructure can mitigate these issues, which is why it can seem so alluring.
And since brokers already have significant experience as an industry in dealing with specialised providers, the process is much easier for them than for banks. A broker doesn’t need to become a blockchain company to use digital assets. It can integrate wallet, custody, compliance and transaction tools into the systems it already runs, in the same way it plugged in everything else.
There’s an irony here. Having outsourced so much, brokers are now using crypto to take something back.
The Wallet Is the New Treasury Account
For brokers operating globally, digital assets are less about offering clients a crypto product and more about managing the company’s own money.
The case for digital assets starts with cost. Brokers typically pay processors between 3.5% and 6% of volume, according to a 2026 survey of high-risk merchants by TheFinRate. At, say, $30 million a month, the 4.7% industry median cited by the survey comes to approximately $1.41 million in fees every month, which can be a real burden for the business.
Wallet infrastructure, however, is priced mostly as a subscription. At Cregis, for example, our Business tier costs $9,700 a year and covers up to $20 million in monthly outbound transfers, with a 0.05% charge above that.
For a broker processing $30 million a month, a $400 capacity expansion would cover the additional volume, bringing the annual platform cost to approximately $10,100, before network fees. Customers purchasing larger amounts of additional capacity upfront can also benefit from volume-based discounts, further reducing the overall cost. The economics are completely different.
Then there’s custody risk. Under the pooled payment-provider model, brokers have to keep large, pre-funded balances with the payment company on an ongoing basis. If that provider runs into trouble, the broker is directly exposed, and so are its clients’ funds. Holding funds in wallets the broker controls, governed by its own permissions and approval workflows, takes that counterparty out of the equation.
Processors typically also withhold around 9% of monthly volume in rolling reserves. So, at $30 million a month, that’s roughly $2.7 million sitting with a third party.
Finally, there’s the customer. Under the gateway model, withdrawals depend on the payment company processing them. Even at large, regulated brokers, card and wire withdrawals are measured in days. FxPro tells clients that international wires take three to five working days and card refunds around ten days. FXCM warns that card refunds can take up to a full billing cycle.
Delays feed anxiety about whether funds are safe and when they’ll arrive, and the broker, under the current model, cannot do anything about it.
Under self-managed wallets, however, withdrawals can occur in a matter of minutes, meaning that a broker can get much closer to the near-instant withdrawals customers have come to expect from major crypto exchanges.
Put together, a well-structured wallet infrastructure becomes the operational layer through which a broker manages balances, moves funds between entities and controls treasury across jurisdictions.
That matters more in forex than almost anywhere else. Brokers serve customers across countries with different banking systems, currencies and payment rails. The more fragmented the footprint, the more valuable it is to reduce dependence on local banking rails and the intermediaries attached to them.
Owning the Stack Becomes the Edge
More than half of Cregis’s clients now come from outside the crypto-native sector, with traditional financial businesses accounting for a significant share. FX brokers make up the largest segment within this group.
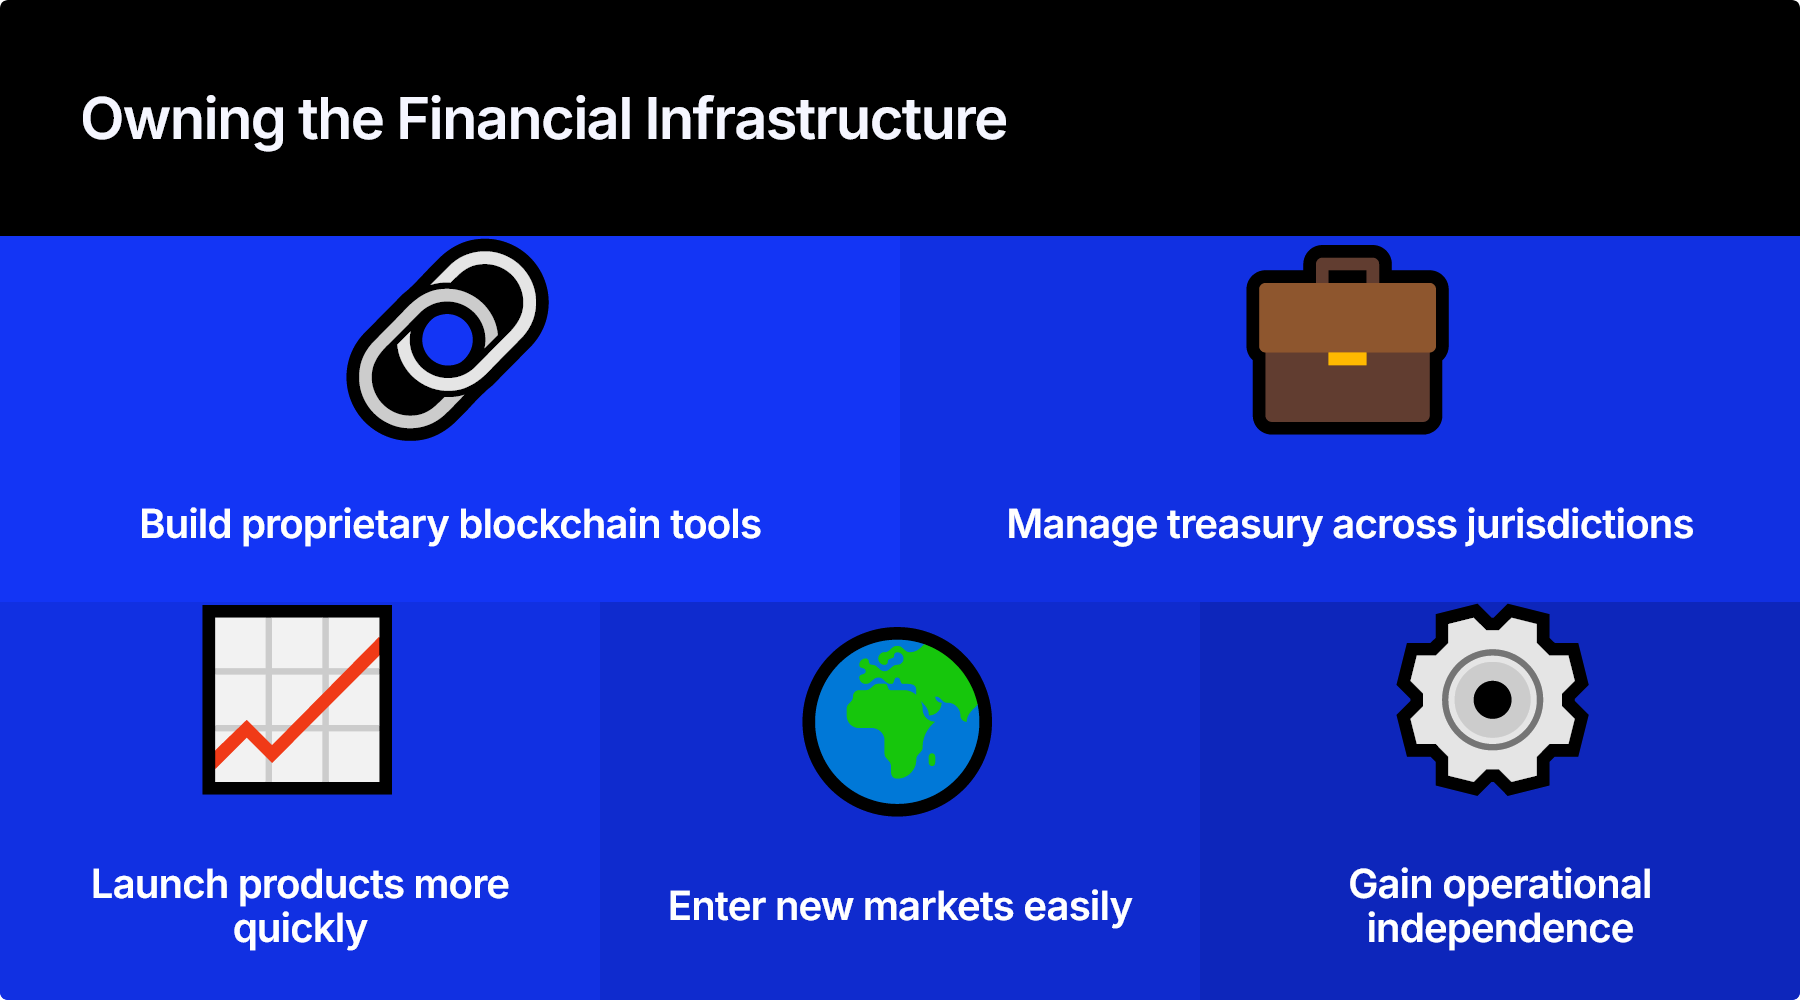
That’s because, over time, these advantages compound. A broker that owns its liquidity, settlement and treasury flows can launch products faster, since it isn’t waiting on a partner’s roadmap. It can enter new markets more easily because it isn’t rebuilding banking relationships from scratch in each one. And it is less exposed when any single bank or payment provider changes its terms or exits a market.
That is how infrastructure ownership moves from a back-office decision to a competitive advantage. The brokers that get there first will set the standard for what customers expect: instant funding, predictable withdrawals and fewer excuses. The rest will find themselves explaining delays their competitors no longer have.


